

There are moments in public life when a single transaction reveals deeper fault lines in governance, accountability and fiduciary responsibility.
The proposed purchase of Amaryllis Hotel by the Public Service Pension Trust Fund (PSPTF) is one such moment.
This is a national controversy that raises troubling questions about transparency and the safety of workers’ retirement savings.
The figure is staggering: K128.75 billion. This is the amount the pension fund proposed to spend acquiring the hotel, using contributions made by thousands of public servants who trust the system to safeguard their future.
These are teachers, nurses, police officers and all picnic servants who contribute a portion of their salaries to secure dignity in retirement.
- Advertisement -
Their savings are not meant for experimentation. They are meant to be protected.
The first red flag is the unexplained escalation in the hotel’s valuation. Just one year earlier, the same property was reportedly valued at K47 billion.
Yet by November 2025, the price had surged to more than K128 billion, effectively tripling in less than twelve months.
Such a dramatic increase defies normal market logic. Property values do rise, but rarely at such a pace without clear structural improvements or extraordinary economic shifts.
- Advertisement -
- Advertisement -
This raises the obvious and uncomfortable question: what changed?
The public has not been provided with a satisfactory answer. Were independent valuations conducted? Were internationally recognised valuation standards followed? Or was the price simply inflated?
Without transparency, suspicion naturally fills the void. Pension funds are not private venture capital vehicles.
They exist to preserve capital and generate stable long-term returns. Any investment that appears to gamble with contributors’ money demands rigorous scrutiny.
The governance concerns do not end there. Reports indicate that the PSPTF board had initially rejected the deal after expert advice deemed it unviable, only for a newly reconstituted board to approve it later.
This reversal is deeply troubling. It suggests either that new information emerged to justify the purchase or that institutional judgement shifted under circumstances that have not been fully explained.
In matters involving billions in pension savings, such abrupt reversals undermine public confidence.
Equally alarming is the warning issued by the Reserve Bank of Malawi. The Registrar of Financial Institutions cautioned that the acquisition could breach investment regulations and create serious liquidity and concentration risks.
These are not abstract technicalities. Liquidity risk means the fund may struggle to access cash when needed to pay retirees.
Concentration risk means too much money is tied up in a single asset, increasing vulnerability if that investment performs poorly.
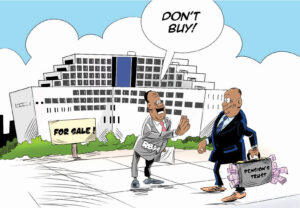 In simple terms, putting such a large share of pension assets into one hotel exposes contributors to unnecessary danger.
Hotels, by their nature, are volatile investments. Their profitability depends on tourism, business travel, foreign exchange stability and overall economic performance.
In our economy, committing such a large amount to a hospitality asset is far from risk free.
A downturn in occupancy rates or operational performance could significantly reduce returns or erode capital.
Even the Anti Corruption Bureau, while finding no clear evidence of criminal wrongdoing, raised serious concerns about operational risks and governance weaknesses surrounding the deal.
This distinction is crucial. A transaction does not have to be criminal to be reckless.
Poor judgement, weak oversight and flawed decision making can be just as damaging to public finances.
The situation is further complicated by institutional disagreement. The Attorney General reportedly viewed the deal as legally defensible, while the Reserve Bank warned of systemic financial risk.
When key state institutions send conflicting signals on a matter of such magnitude, it highlights deeper structural weaknesses in regulatory coordination and oversight.
The broader implications extend beyond this single transaction.
Pension funds represent deferred wages. They are promises made to workers who spend decades serving their country.
Any decision that jeopardises those funds undermines trust not only in pension administrators but also in public institutions.
In the meantime, the public deserves answers.
Who authorised the valuation increase? What due diligence was conducted? Were investment guidelines followed? Were contributors’ interests placed above all other considerations?
These questions remain unresolved.
The hotel deal has exposed dangerous grey areas in governance, valuation transparency and fiduciary accountability.
It has revealed how quickly pension funds can become entangled in high-risk transactions without adequate safeguards.
Most importantly, it has reminded Malawians that the security of retirement savings cannot be taken for granted.
Pension funds must be managed with extreme caution, guided by prudence rather than ambition.
When billions in retirement savings are at stake, there is no room for speculation, secrecy or shortcuts.